Artigo redigido com a ajuda de IA.
Before Trading AI Proxies, Price the Basis Risk
AI proxy stocks often move on stories that are adjacent to the AI thesis, not identical with it. Before sizing the trade, the cleaner question is whether the listed instrument’s exposures, liquidity, spread, market depth and exit cost still justify using it as the expression.
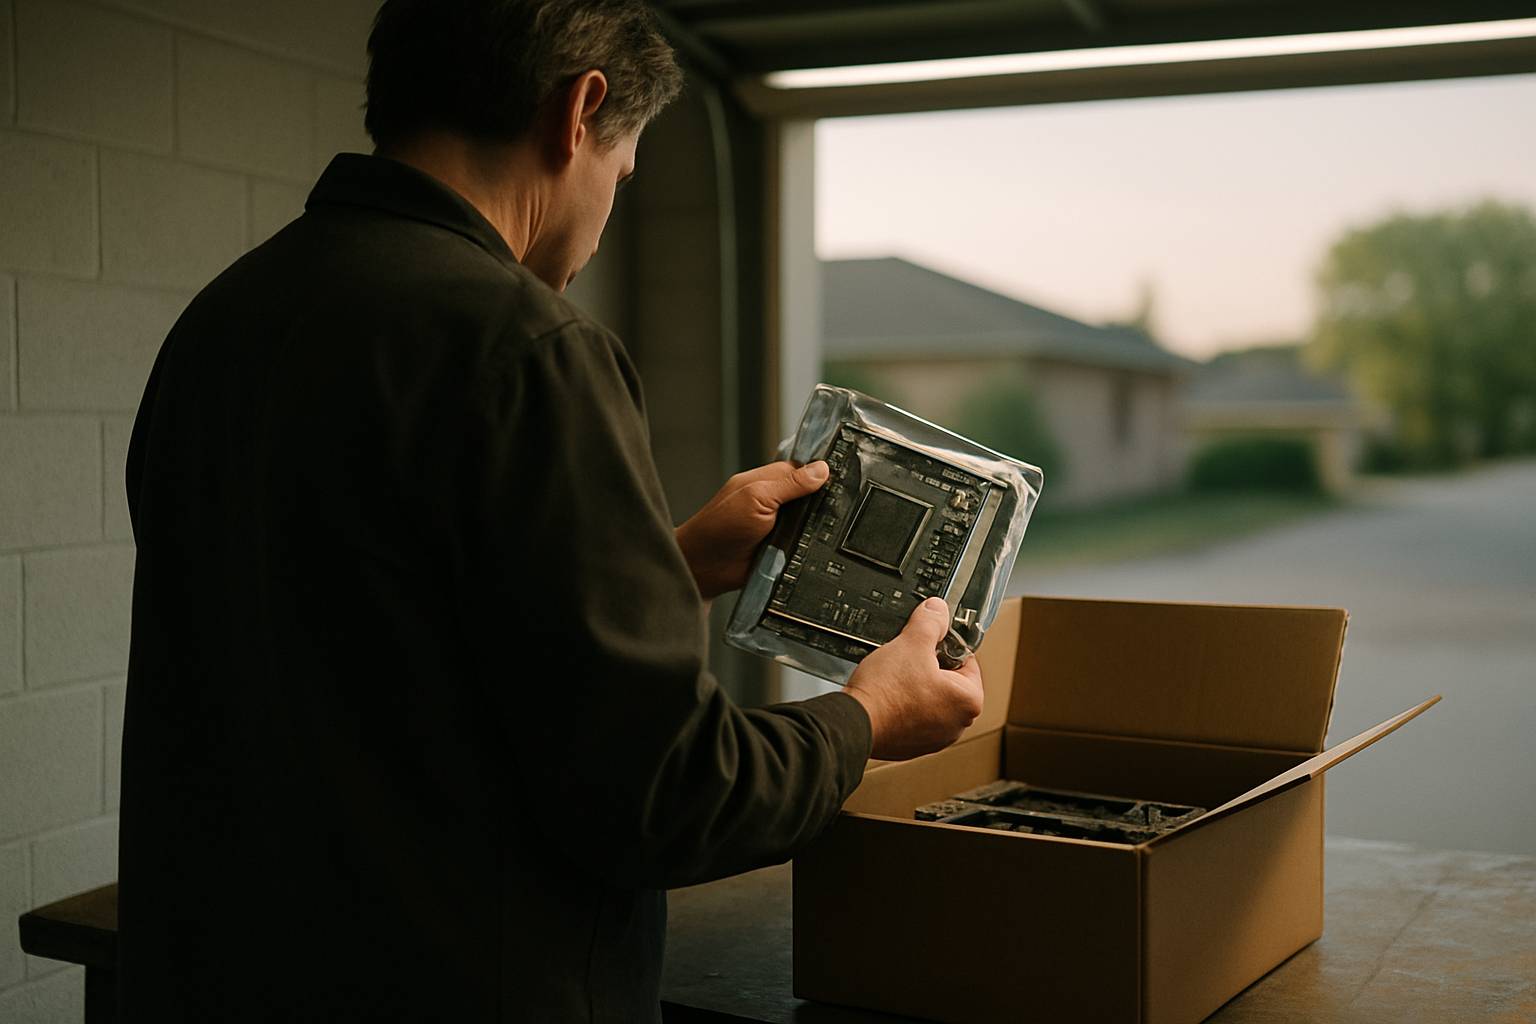
The order looks like an AI trade until the quote screen reminds the trader that the instrument is Tesla, an ETF, or another listed proxy with its own balance sheet and order book.
That distinction matters. A headline about OpenAI, model demand, data-center buildout, autonomous systems, or AI infrastructure can push listed securities that are only loosely connected to the underlying story. The trade then contains two things at once: the intended AI view and the unwanted gap between that view and the instrument used to express it.
That gap is basis risk. In AI proxy stocks, it is often the main risk on the ticket.
The AI headline is not the same as the trade
A headline can be clean. The trade rarely is.
The intended view might be simple: AI demand is increasing, a particular platform is gaining relevance, or capital is moving toward companies perceived to benefit from the theme. But if the listed instrument is a diversified company, an electric-vehicle maker, a supplier, or an ETF with several unrelated holdings, the position is not a pure AI exposure.
A recent Tesla example shows the problem clearly. MarketWatch published a piece framing Tesla as a company that could reshape trucking and benefit from elevated diesel prices. The source describes Tesla as an electric-vehicle maker and says the company is trying to advance its Semi truck program after a long wait. It also attributes to Morgan Stanley the view that Tesla’s Semi effort could represent a very large opportunity.
That is not a direct OpenAI catalyst. It is not, from the available source, a direct AI-infrastructure catalyst either. It is a Tesla story tied to electric trucks, trucking economics, diesel prices, and execution of the Semi program.
A Tesla order entered as a broad AI proxy would therefore be carrying exposures that are not AI exposures. The data available here does not establish whether Tesla shares moved in response to this specific Semi-related coverage. It also does not provide valuation, revenue, margin, delivery, spread, depth, or market-impact estimates. Those unknowns are not footnotes. They are the point.
Define what the proxy actually owns
The first part of pre-trade analysis is not a view on AI. It is instrument definition.
For a single stock, the question is what the company actually does and what can move the stock independent of the AI theme. In the Tesla example, the available source identifies the company as an electric-vehicle maker and discusses its Semi truck program. A trader using Tesla as an AI proxy is not only buying sensitivity to AI-related narratives. The position can also react to vehicle manufacturing, trucking adoption, energy prices, program delays, competitive dynamics, and investor expectations around the Semi opportunity.
For an ETF or basket, the same problem appears in a different form. The instrument may contain AI-related names, but it may also contain stocks whose earnings drivers have little to do with the specific headline being traded. The exact Tesla weight, the overlap with the intended AI exposure, and the non-AI holdings would need to be known before the instrument can be treated as a useful proxy. The briefing does not provide those weights or overlaps, so they cannot be assumed.
This is where portfolio risk assessment begins. Not with the headline, but with the holdings, revenue drivers, and exposures that will actually sit in the account after execution.
Check portfolio overlap and revenue sensitivity
Basis risk becomes more expensive when the proxy overlaps with existing positions or when the chosen stock has low sensitivity to the intended story.
If the portfolio already contains electric-vehicle exposure, large-cap growth exposure, or other positions that tend to move with Tesla, adding Tesla as an AI proxy may concentrate risk rather than add clean AI exposure. The trade can appear diversified by theme while remaining concentrated by factor, sector, liquidity profile, or narrative.
Revenue sensitivity is the second layer. The available briefing does not tell us how much of Tesla’s current valuation or expected earnings is tied to AI-related businesses versus vehicle manufacturing, energy, software, or trucking. That uncertainty should not be filled with a guess. If the trade thesis depends on AI, but the source material being traded is about trucking and diesel economics, the position is exposed to tracking error between the thesis and the stock’s actual earnings debate.
That tracking error is not just a performance statistic after the fact. It is a pre-trade cost. It affects position sizing because it changes what the position is expected to hedge, amplify, or diversify.
Compare the proxy move with the underlying AI story
An AI headline can lift several listed names at once, but that does not mean each move is expressing the same thing.
One stock may be moving because investors see direct demand. Another may be moving because it is already a liquid way to express the theme. A third may be moving because it is caught in a broad basket rebalance. A fourth may be moving on a completely different story that happens to sit next to the AI narrative on the same ticker.
The Tesla Semi example is useful precisely because it is adjacent. A trader may think of Tesla as an AI proxy in some contexts, but the MarketWatch item described in the briefing is about trucking, electric trucks, elevated diesel prices, and the advancement of the Semi program after a long wait. If that is the active headline, the trade is not primarily a view on AI demand. It is at least partly a view on whether the market will capitalize a trucking opportunity inside Tesla.
The data does not settle whether that story changed the share price. It does not settle whether the Semi opportunity is already priced. It does not settle how much of the market’s Tesla debate is tied to AI rather than vehicles or trucking. A disciplined AI trading analysis has to leave those blanks visible.
Price the spread, depth, and likely slippage
After the thematic fit comes the order book.
A proxy can be directionally attractive and still be a poor trade at the displayed price. The bid-ask spread, market depth, and expected slippage determine how much of the thesis is consumed by execution before the position has a chance to work.
For a liquid single stock, the visible spread can make the trade look cheap. That can be misleading if the intended order is large relative to displayed depth at the best bid and offer, or if liquidity fades when the headline is active. For an ETF or basket, the screen price can hide another layer: the liquidity of the underlying holdings and the efficiency of the creation-redemption mechanism. The briefing does not provide current bid-ask spread, displayed depth, average daily volume, or market-impact costs for Tesla or any Tesla-linked proxy. Those inputs must remain unknown here.
That uncertainty has a direct consequence. No pre-trade cost estimate can honestly claim that a proxy is cheap to trade without measuring the actual quote, depth, likely fill path, and slippage under current conditions.
Liquidity analysis should also distinguish between entering and exiting. It is common to model the entry carefully and assume the exit will be available. In headline trades, that assumption is often where execution risk hides.
Model the exit before entering the position
Exit liquidity is not the same as entry liquidity.
The entry often happens when attention is rising and counterparties are present. The exit may be needed when the story has cooled, when the proxy has decoupled from the original theme, or when the non-AI exposure starts driving the price. A Tesla position opened as an AI proxy can later be marked by Semi news, electric-vehicle sentiment, trucking economics, or energy-price assumptions. The trader may still be right about AI and wrong on the instrument.
The exit model should ask what has to be sold, not what was originally bought in the trader’s mind. A share position needs stock liquidity. An ETF position needs ETF liquidity and underlying basket liquidity. A basket trade needs liquidity in each component, especially the names that are hardest to unwind when the theme reverses.
The cost is not only spread. It is spread plus slippage plus market impact plus the chance that the proxy no longer tracks the intended AI story when the exit signal arrives.
That is basis risk expressed through execution.
Size the order as a basis-risk trade, not a pure AI view
Position sizing should reflect the instrument’s impurity.
A clean thematic view can justify one risk budget. A proxy with uncertain sensitivity deserves another. If the trade depends on an AI story but the instrument is exposed to electric trucks, diesel economics, program execution, and broader vehicle sentiment, the size should account for those additional drivers.
This does not mean the trade is wrong. It means the risk unit is different. The position is not sized only against the AI catalyst. It is sized against the possibility that the market prices a different story on the same ticker.
The Tesla example makes this concrete. The available source says Morgan Stanley views the Semi effort as a very large opportunity, but it does not provide the underlying estimates. It does not show how much of Tesla’s valuation is tied to that opportunity. It does not tell us the current execution cost of a Tesla trade. A position that ignores those gaps is not an AI proxy trade with a small uncertainty around it. It is a basis-risk trade with an AI label attached.
A practical pre-trade checklist for AI proxy stocks
A useful checklist is short enough to run before the order and specific enough to change the order.
- What is the actual catalyst: AI demand, OpenAI-related sentiment, data-center demand, trucking economics, energy prices, or company-specific execution?
- What does the proxy actually own or operate?
- Which non-AI exposures can move the instrument during the intended holding period?
- Does the portfolio already contain overlapping exposure to the same stock, sector, factor, or theme?
- Is the revenue or valuation sensitivity to the AI story known, or is it being assumed?
- Has the proxy historically tracked the intended story closely enough for this trade, or is tracking error likely to dominate?
- What is the current bid-ask spread?
- How much displayed market depth is available at and near the touch?
- How much slippage is likely for the intended order size?
- Is the exit likely to be available under worse conditions than the entry?
- What breaks the trade: the AI thesis, the proxy relationship, or the execution assumptions?
The strongest part of this checklist is not the list itself. It is the discipline of separating the story from the instrument before deciding size.
When the basis risk is too high to justify the trade
Some proxy trades fail before the first fill.
Basis risk is too high when the listed instrument can move materially for reasons unrelated to the intended AI view and those reasons cannot be measured well enough before entry. It is too high when portfolio overlap turns a thematic expression into concentration. It is too high when the spread and depth make the expected slippage large relative to the trade thesis. It is too high when the exit depends on liquidity that is visible now but unlikely to be present when the position needs to be unwound.
The Tesla Semi case does not prove that Tesla is a poor AI proxy. The available data is not sufficient to make that claim. It does show why the label is not enough. A stock discussed in connection with a very large electric-truck opportunity and elevated diesel prices is carrying a different set of drivers from a direct AI-infrastructure catalyst.
That difference has a price.
Pre-trade analysis is the place to find it. Not after the fill, not after the proxy stops tracking the headline, and not when the exit book is thinner than expected. Before trading AI proxy stocks, the cleaner question is whether the basis risk is being paid for, controlled, and sized — or merely renamed as conviction.